Partner at AKD Lawyers
Practice Areas: Personal Injury, Insurance Claims

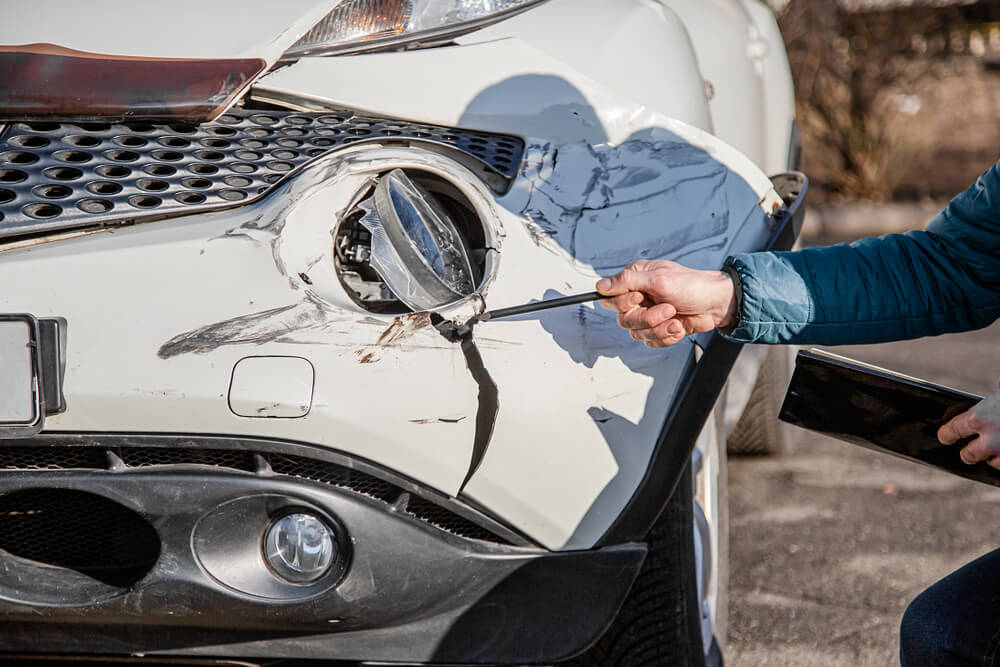
Getting your car back from the body shop does not always mean you are back where you started financially. Even after a proper repair, an accident in the vehicle’s history can make it harder to sell or trade for the same price it would have brought before the crash.
That loss in value is known as diminished value. Louisiana drivers may be able to recover it in some situations. A New Orleans car accident law firm can help you figure out whether it applies to your car and what evidence you need.
What Diminished Value Means
Diminished value is the difference between what a vehicle was worth before an accident and what it is worth after the repairs are finished.
The car may look fine when you pick it up. But once the accident is listed on its history, a buyer or dealer may offer less. That history can affect the car’s value even when the repairs were done properly.
Say your 2022 SUV was worth $35,000 before the accident. After the repairs, you may find that buyers would only pay around $30,000. That $5,000 gap is the diminished value, a financial loss caused by the accident that a repair bill does not cover.
The Three Types Of Diminished Value
Knowing which type applies helps you frame your claim.
Immediate diminished value is the drop right after the crash but before repairs, when the car is damaged and undrivable. Insurers rarely pay for this since it is temporary.
Inherent diminished value is the most common and widely accepted form. It is the permanent loss in resale value that remains even after proper repairs, because buyers avoid cars with an accident record.
Repair-related diminished value happens when the quality of the work itself lowers the car’s worth, such as aftermarket parts instead of OEM parts, mismatched paint, or minor alignment issues.
How Insurers Calculate It
Louisiana does not require insurers to use a single formula for diminished value. Some insurance companies use the 17c Formula, but it can produce a number that is lower than the vehicle’s actual loss in value.
The formula works like this:
- Start with the car’s pre-accident value. Insurers may use Kelley Blue Book, NADA Guides, or similar sources.
- Apply the 10% cap. The formula limits the starting loss to 10% of the vehicle’s pre-accident value.
- Account for the damage. A multiplier is used based on how serious the damage was, such as 0.25 for minor damage, 0.50 for moderate damage, or 1.00 for severe damage.
- Factor in mileage. Older vehicles and those with more miles generally receive a lower figure.
Take a $30,000 car as an example. The 10% cap would put the starting loss at $3,000. With moderate damage, that could drop to $1,500 before the mileage adjustment.
The 17c Formula comes from the Georgia case State Farm v. Mabry (2001). Louisiana does not require insurers to use it, so the formula’s result is not necessarily your car’s actual market-value loss. An independent appraisal may give you a more accurate figure.
Get Your Free Consultation
Louisiana Law On Diminished Value Claims
You would usually pursue diminished value from the driver who caused the accident. If you were partly at fault, the amount can be reduced. Louisiana’s current rule cuts off recovery at 51% fault for crashes covered by La. Civ. Code art. 2323.
The timing depends on when the crash happened. For accidents on or after July 1, 2024, La. Civ. Code art. 3493.11 gives you two years to bring the claim. Do not let the deadline pass while you are still negotiating with an insurer.
Your own policy may not help with diminished value. Some policies cover it; others do not, so you need to check the policy language.
How To Estimate And File A Claim
A diminished value claim needs evidence, not just a phone call.
| Step | What it involves | Why it matters |
|---|---|---|
| Appraisal | Hire an independent vehicle appraiser | Establishes the true post-repair loss |
| Documentation | Gather repair invoices, photos, value reports | Provides objective proof |
| Demand letter | Submit to the at-fault insurer | Starts the official review |
| Negotiation | Compare insurer vs. appraiser figures | Pushes toward a fair number |
| Legal review | Optional if a dispute continues | Protects your rights within the deadline |
Insurers tend to open low, so a credible appraisal strengthens your position considerably.

Common Mistakes To Avoid
Many drivers do not realize they can claim more than the repair bill.
A few common mistakes can get in the way:
- Assuming the repair bill covers everything
- Assuming their own policy covers diminished value
- Waiting too long to make the claim
- Not keeping photos, records, or other proof
Knowing what you can claim and keeping the right records can make a difference.
Frequently Asked Questions
What qualifies as diminished value after a crash?
It is the measurable drop in your car’s resale or trade-in value after an accident, even when every repair is done properly, and the car looks new.
Can I file if I was partially at fault?
Yes, but your percentage of fault affects what you can recover. A person who is 20% at fault, for example, can still recover the other 80% of the damages.
Does my own insurance cover diminished value?
Usually, no. It depends on the policy. Some coverage may include diminished value, but a standard policy does not automatically pay for the drop in value after repairs.
How do I prove diminished value?
An appraisal can show what the vehicle was worth before and after the accident. Its repair history, accident history, and prices for similar vehicles can support the amount.
What if the insurer’s offer is too low?
You can challenge it with an appraisal and other market evidence. If the insurer will not adjust the offer, consider speaking with a lawyer before accepting it.
Have Questions About Your Car’s Lost Value?
Diminished value is one of the most overlooked losses after a crash, and insurers count on drivers not knowing about it. If you believe your car lost value because of someone else’s negligence, Alvendia, Kelly & Demarest can help you push for a fair number.
Call (504) 200-0000 for a free consultation. No fee unless we win. Reach out today.
Reviewed by J. Bart Kelly, III, Partner at Alvendia, Kelly & Demarest Law Firm.
Categories
In 2003, after being dissatisfied with the quality of legal care for victims of car accidents, Roderick ‘Rico’ Alvendia sought to establish a new firm focused on providing high-quality legal services to aid injured victims and their families. J. Bart Kelly, sharing Rico’s passion for upholding justice, joined the firm later that year, and established a partnership.